From 40% to 8%: How Huawei's Ascend 950 Is Ending Nvidia's China Era
Bernstein forecasts Nvidia's China AI chip share will collapse to single digits in 2026 while Huawei climbs toward 50%. The story behind the numbers is a state-orchestrated industrial substitution unfolding faster than almost anyone predicted.
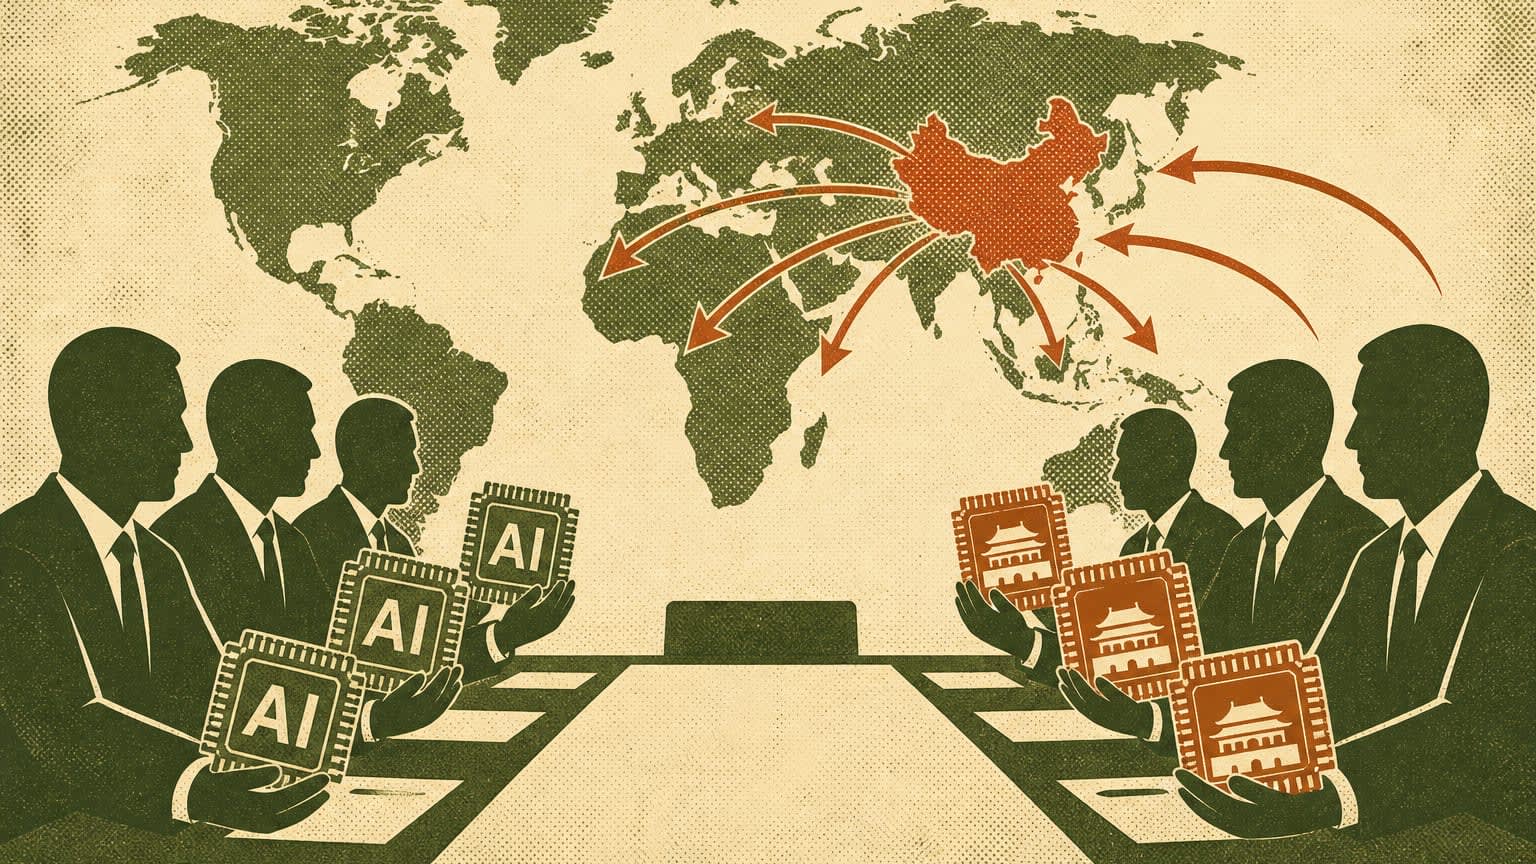
Two years ago, Nvidia owned roughly 40 percent of China's AI chip market even under export restrictions. By the end of this year, Bernstein projects that share will be 8 percent — with Huawei climbing toward 50 percent. If the forecast holds, it will mark one of the fastest market-share collapses in semiconductor history, and the clearest evidence yet that US export controls have accelerated exactly the outcome they were designed to prevent.
How the substitution actually happened
The mechanics are worth spelling out, because they were not inevitable. Three forces converged:
Supply-side scaling. Huawei's Ascend 950 line finally hit volume production, with SMIC yields improving enough to matter and packaging bottlenecks easing. Beijing's directive to triple domestic AI chip output gave every state-linked buyer a mandate to absorb that supply. Reports indicate Huawei is deliberately ramping production to fill the vacuum Nvidia is leaving.
Demand-side coercion and confidence. Chinese regulators spent 2025 discouraging domestic champions from buying the H20 and its successors — sometimes explicitly. But the softer force was proof of viability: when Zhipu completed a 1-gigawatt data center running entirely on domestic silicon, and DeepSeek and Moonshot demonstrated frontier-class training runs on mixed Chinese hardware, the perceived performance penalty of going domestic shrank from existential to manageable.
Washington's own hand. Each new restriction — the May move against overseas subsidiaries, the August push to close the cloud-rental loophole — reinforced the message that Nvidia supply can vanish with a Federal Register notice. No procurement chief builds a five-year roadmap on that.
Nvidia's inference gambit
Nvidia is not conceding. Its Groq-derived inference chip, expected in small volumes by year-end, targets the one segment where domestic alternatives remain weakest: low-latency inference at scale, where software maturity and interconnect still favor Nvidia's stack. Jensen Huang's planned Beijing visit signals the company will fight for whatever perimeter remains.
But inference is also where Chinese chips are closing fastest, because inference workloads tolerate heterogeneity far better than training runs. An 8 percent share built on inference parts is a business, not a beachhead.
What the endgame looks like
The deeper story is that the world is bifurcating into two semi-independent AI hardware stacks. One runs on Nvidia and TSMC; the other, increasingly, on Huawei and SMIC. Sovereign AI buyers from the Gulf to Southeast Asia now genuinely have two catalogs to shop from — Saudi Arabia's HUMAIN building on Chinese model weights while buying American chips shows how mixed those procurement decisions have become.
For Huawei, the prize extends beyond China. Every Ascend cluster sold domestically funds the software ecosystem — CANN, MindSpore, and a growing porting industry — that makes the next export sale easier. The 40-to-8 collapse is not just Nvidia losing China. It is China gaining an export platform.
Newsletter
Get Lanceum in your inbox
Weekly insights on AI and technology in Asia.
More in Analysis
All Three Majors Are Now Suing Anthropic. The AI Copyright Endgame Is Taking Shape
The Backlash Has Arrived: Asia's Data Center Boom Is Colliding With the People Who Live Next Door